Do Pennsylvania contractors need commercial auto insurance?
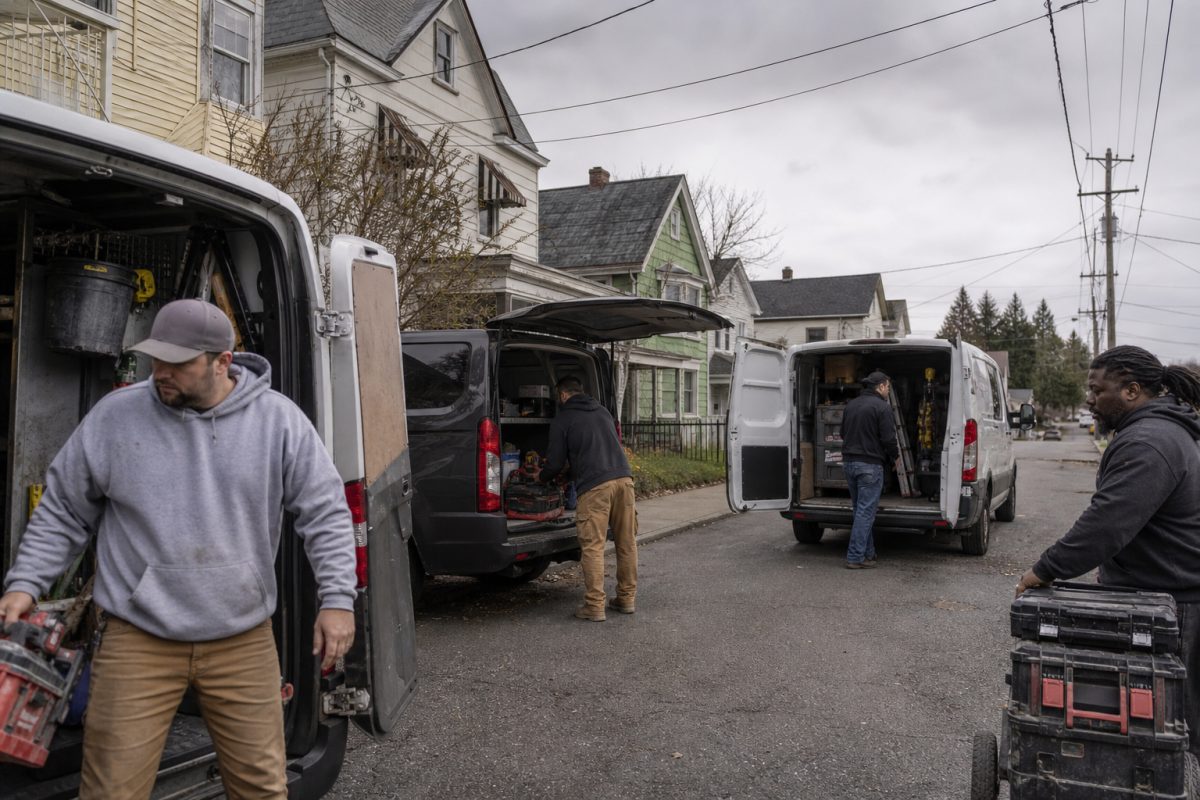
Yes, Pennsylvania contractors usually need commercial auto insurance when a vehicle is used for business, because personal auto policies often do not fit contracting work. This applies whether you drive to job sites, pick up materials, visit clients, or send employees in company vehicles. The right policy depends on who owns the vehicle, how it is used, and what kind of contracting work you do.
Why personal auto may not be enough
A personal auto policy is built for household driving, not regular business use. If a contractor uses a pickup, van, or other vehicle to haul tools, tow equipment, visit job sites, or make business stops, the insurer may treat that use differently from commuting or personal errands.
A claim can become more difficult when the vehicle is titled personally but used for contracting work. For example, a crash on the way to a job site or supply house may raise questions about whether the policy should respond. Commercial auto insurance is designed to account for business use, but the exact coverage depends on the policy and carrier.
Pennsylvania generally requires vehicles operated on public roads to be insured. Contractors should also make sure the coverage matches the way the vehicle is actually used, especially when clients, landlords, general contractors, or lenders ask for proof of commercial auto coverage.
What commercial auto usually covers
Commercial auto insurance typically includes liability coverage for injury or property damage caused by an insured vehicle. It may also include coverage for damage to the contractor’s own vehicle if physical damage coverage is selected.
For contractors, the policy may be written for pickups, vans, box trucks, dump trucks, trailers, and other business vehicles, depending on carrier rules. Coverage can also be adjusted for employees who drive, business locations, vehicle ownership, and whether vehicles are used across state lines.
Some contractors need hired and non-owned auto coverage. This can apply when the business rents a vehicle, borrows a vehicle, or has employees use their own cars for work errands. It is not a substitute for insuring company-owned vehicles, and policy wording matters.
Common contractor gaps
Tools and equipment inside a vehicle are a common source of confusion. Commercial auto insurance may cover the vehicle itself, but tools, materials, and equipment often need separate coverage, such as inland marine or contractor equipment insurance. KAMFS Inc. can help review where the vehicle coverage ends and where another policy may be needed.
Another gap can happen when employees drive vehicles that are not properly listed or when a vehicle is added to the business but not reported. Contractor vehicles change often, so the policy should be updated when vehicles are bought, sold, leased, or assigned to different drivers.
A business owners policy or general liability policy also does not replace commercial auto insurance. Those policies may help with certain premises or operations claims, but auto accidents involving business vehicles are usually handled under an auto policy.
How KAMFS Inc. helps Pennsylvania contractors
KAMFS Inc. works with contractors to understand how vehicles are used during the workday. That includes the type of contracting trade, vehicle ownership, driver details, job site travel, towing, equipment hauling, and contract requirements.
Because KAMFS Inc. is an independent, licensed property and casualty insurance agency, it can place coverage with admitted carriers and wholesale markets when needed. Availability, pricing, limits, exclusions, and driver eligibility vary by policy and carrier.
Contractors should review coverage before signing a lease, accepting a contract, buying a vehicle, or letting employees drive for work. A short review can often identify whether the business needs a commercial auto policy, hired and non-owned auto coverage, or related coverage for tools and equipment.
More on this topic: Commercial Auto Insurance and KAMFS Inc. in Pennsylvania.
Common Questions
Can my employee drive a company vehicle home?
Often, yes, but the policy should reflect who drives and how the vehicle is used. Personal use, take-home vehicles, and household drivers can affect underwriting and coverage terms.
Does commercial auto cover tools stolen from my truck?
Not always. Tools and equipment are often better addressed through inland marine or contractor equipment coverage, subject to policy terms and exclusions.
Do I need coverage if I only use my own pickup for jobs?
You may still need commercial auto coverage if the pickup is used for contracting work. Personal auto policies can limit or exclude business use, so it is best to review the details with KAMFS Inc.
Questions about your coverage? Call KAMFS Inc. at (347) 475-1552 or email info@kamsurance.com.